Blog · Long-term care
Why Buy Long-Term Care Insurance?
Are you risking your retirement assets by not having Long-Term Care insurance? When health care related expenses occur in retirement, the extra income taken from existing assets may jeopardize an otherwise robust retirement plan.
The risk is this: 70% of those over of 65 will need some type of long-term care. If you are developing your retirement plan, consider this risk and the potential impact on lost assets in retirement. These losses may impact your standard of living, your spouse, and maybe your children’s time and finances.
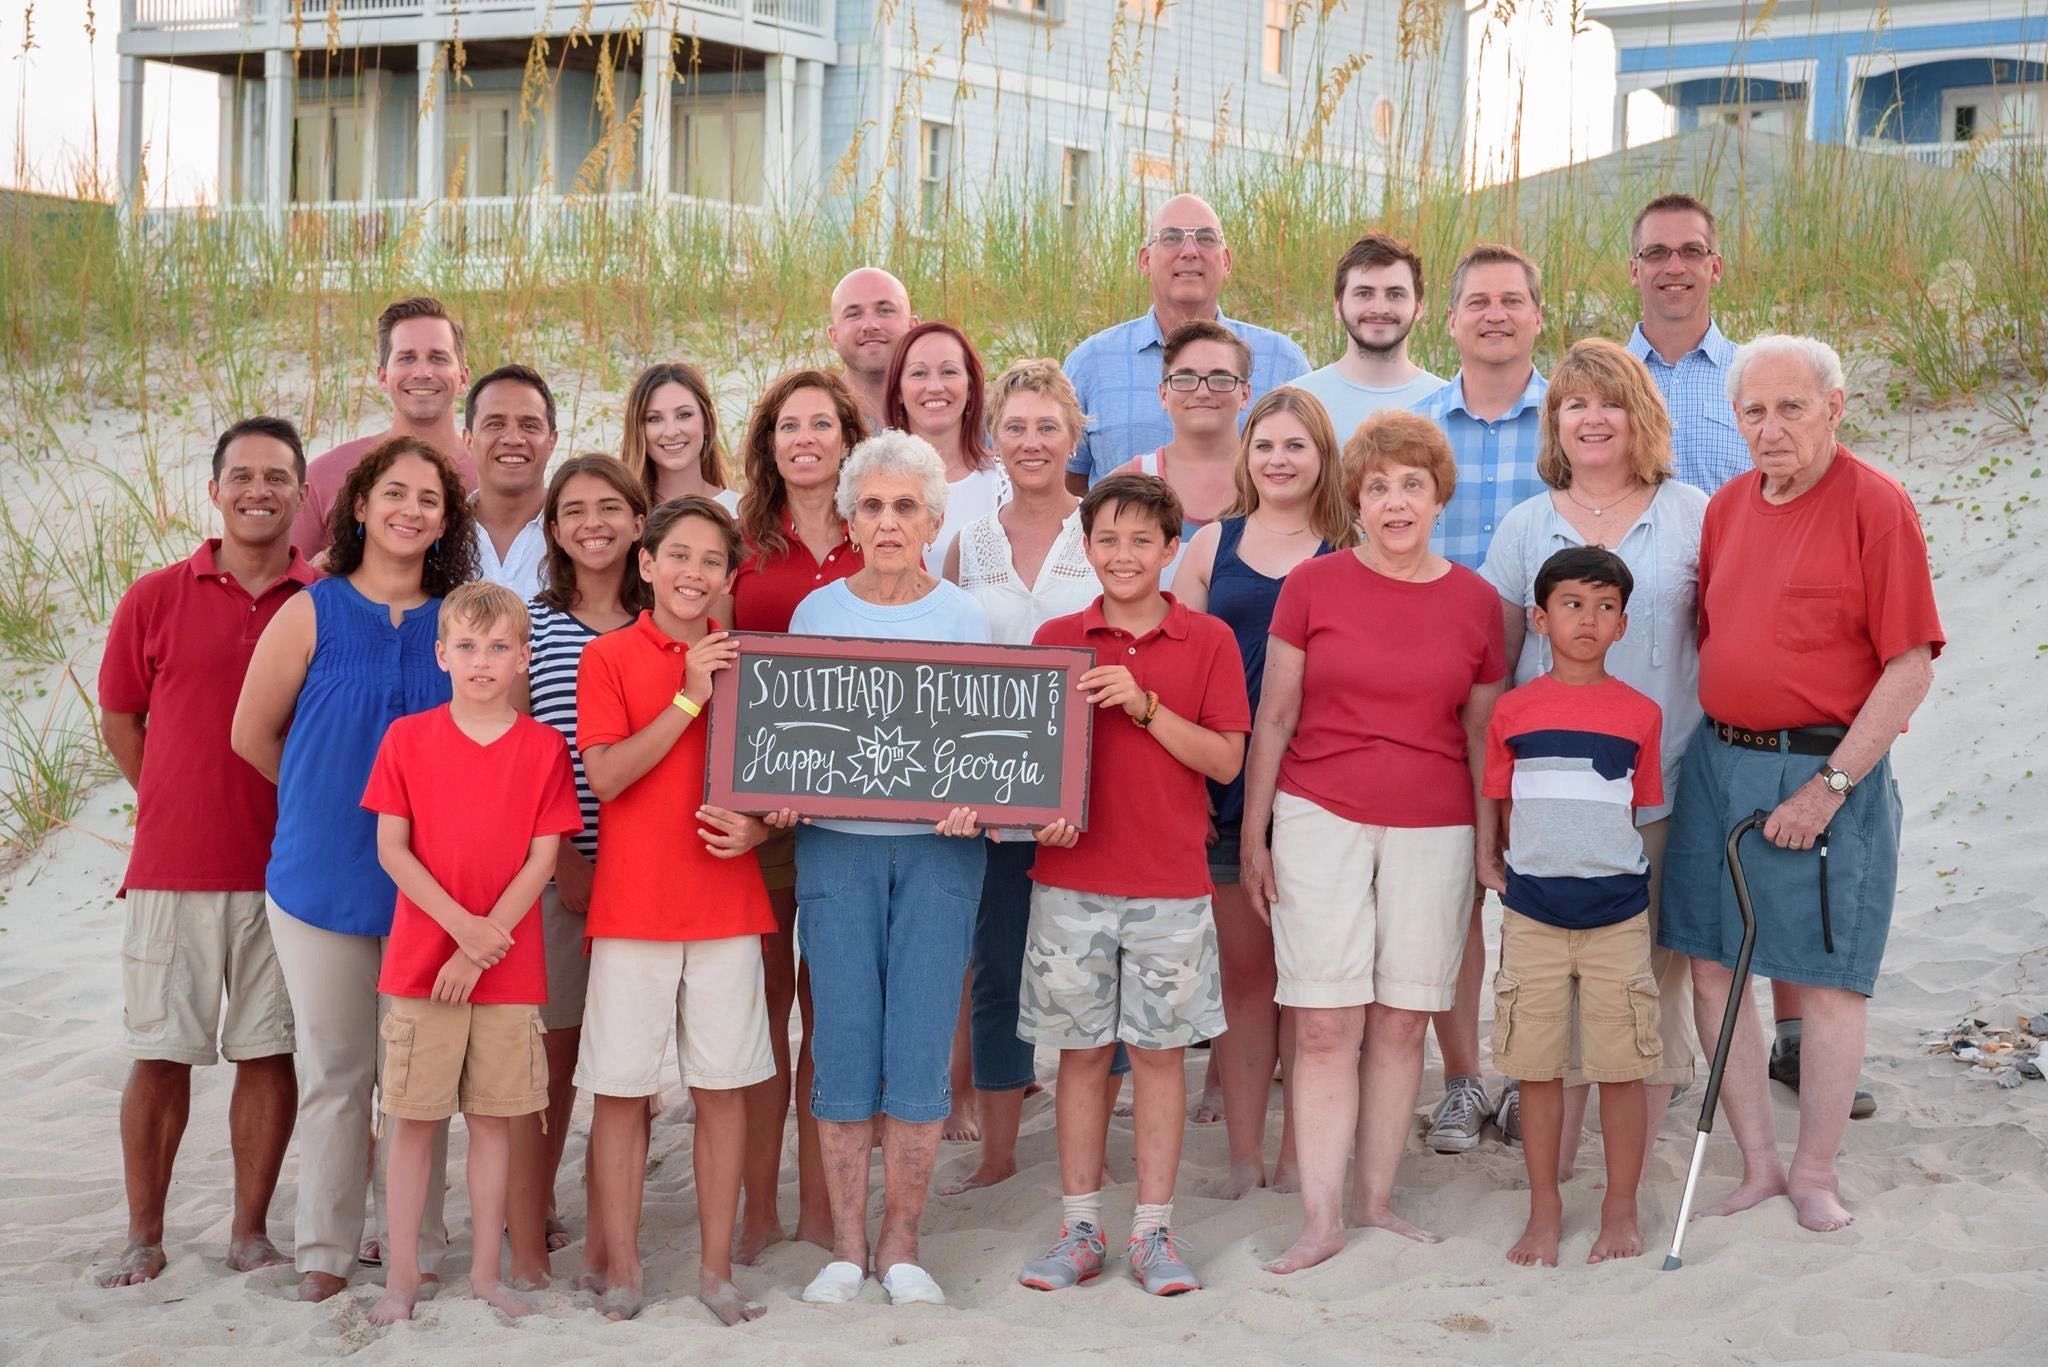
My parents grew up in the depression era following WWI and then lived through WWII, in which my dad served. After those trying times, my parents sought noble and stable careers as teachers, expecting stable income and decent retirement plans. Not a career to get rich in, but with humble and frugal origins, they lived comfortably. Retirement years were short for my dad, passing at 71. My mom (pictured above at 90) lived to nearly 93.
As my mom aged, she moved from independent living in her own apartment to an assisted living facility. During her later years she remained mostly ambulatory, though she could no longer prepare meals, dress, bathe or manage other hygiene needs on her own. I’m extremely grateful my sister lived near her during this time. She gracefully took on managing our mother’s finances and hired the in-home care she needed, when she needed it. Just being there to help with so many life decisions was crucial.
Long-Term Care insurance played an important part in stretching our mother’s pensions, social security, and savings. Having these resources allowed my sister to make the best choices for our mom’s assistive care while allowing my mother the most autonomy in living arrangements. All accomplished without any financial assistance from her children as my mother hoped.
I share these personal details hoping to illustrate the various needs we face as we age. As you’ll note in the definitions of ADLs and IADLs below, you may think back to my story and the many additional aspects of care beyond what medical professionals provide.
Will you likely need LTC?
-
70% of those over 65 will need some form of long-term care.
-
Average need for women: 3.7 years; men: 2.2 years.
-
20% will need 5+ years
What is Long-Term Care (LTC)?
-
Broadly defined, this care consists of services one may need to address physical, not medical needs.
-
Most often, family members and friends provide this kind of care.
-
Categories of LTC:
o “Activities of Daily Living” (ADLs), typically defined as these six: Bathing, Dressing, Toileting, Transferring, Incontinence, and Eating (not meal prep).
o Instrumental Activities of Daily Living (IADLs) are another category of services, inculding: housework, money management, food prep and cleanup, grocery and household shopping, communication, pet care, handling emergencies alerts (such as fire).
What about Medicare and Medicaid?
For those qualified, Medicare may cover rehabilitative and skilled nursing care up to 100 days. Beyond that, Medicaid (MediCal in CA) may provide LTC if you qualify (state defined eligibility). You need to be near the federal poverty limit with income and few assets.
What are the LTC insurance options?
-
Traditional – limited pool of money with maximum monthly benefits. Usually no residual benefit to beneficiaries. Premiums may and usually do increase.
-
Hybrid – asset based policy pays depletes value as benefits are used, but will also pay out to beneficiaries the unused balance. Fixed premiums. May offer larger pool of benefits than traditional.
-
Living Benefits as riders on some term and most permanent life insurance policies via cash advances on the death benefit for critical, chronic or terminal illnesses.
Please note, Long-Term Care insurance (LTCi) is specifically designed to meet SOME of the LTC expenses in hopes of not draining all retirement resources. It is about risk management. How much do you transfer to the insurance company, and at what cost? With the average costs of in-home aides easily costing over $60,000 / year, retirement savings may be significantly impacted, perhaps jeopardizing the retirement of a surviving spouse. Policies are designed to pay a maximum benefit amount monthly or annually until the designed fund is exhausted. Some hybrid policies offer longer duration of full benefit payout, including a lifetime rider option from OneAmerica (not available in NY State).
Traditional LTCi policies are attractive due to their lower upfront costs. However, like many types of insurance, there is no return of premium. Traditional LTCi policies are also subject to rising premiums or declining benefits.
Hybrid type policies are based on annuities or whole life policies. This results in a payout to beneficiaries as a remainder of funds not spent. Out of the gate they typically cost more but have guarantees of payout and set premiums. I actually prefer a hybrid type from OneAmerica because of guarantees AND lifetime benefits that don’t exhaust (chronic illnesses and cognitive disabilities can last for years).
Living Benefits / Accelerated Death Benefits. Many types of life insurance policies allow for a portion of a death benefit to be distributed in advance following a diagnosis of a critical, chronic, or terminal illnesses. Policy terms and restrictions vary by carrier, state and policy type.
Full disclosure: As a licensed Life & Health agent, I’ve assisted clients in obtaining all of these types of insurance. Also, I personally own a hybrid type LTCi policy from OneAmerica and an IUL Life insurance policy with living benefits from Ameritas.
Be sure to read this reference prepared by the National Association of Insurance Commissioners (NAIC): A Shopper’s Guide to Long-Term Care Insurance
What should you do?
If you are over 45, have a discussion with your insurance agent about your retirement plans and budget. Please don’t wait until you’ve developed health issues that would exclude you from qualifying for this insurance. You can’t buy fire insurance when your house is on fire. If you can’t qualify for life insurance, there are annuity based options.
For a free consultation, book time on my calendar:
Resources and references:
https://acl.gov/ltc/costs-and-who-pays/what-is-long-term-care-insurance
https://www.hhs.gov/answers/medicare-and-medicaid/who-is-eligible-for-medicaid/index.html
https://www.retirementliving.com/reviews/oneamerica-long-term-care-insurance
2 Minute video by economist and author Tom Hegna on LTC insurance: